Rent-to-own can sound like an attractive solution when a poor credit record prevents you from getting vehicle finance. But the promise of eventually owning a car can come with a lengthy commitment, substantial costs and conditions you need to understand. Before signing, consider a DrivePass subscription.
When you need reliable transport and the bank has declined your application, getting approved elsewhere can feel like the answer.
However, approval is only the beginning. What matters is how much you will pay, how long you must keep paying and what happens if your circumstances change.
Before committing to rent-to-own, compare it with DrivePass, Cars.co.za’s prepaid car-subscription offering.
DrivePass: Virtually new cars without a long-term commitment
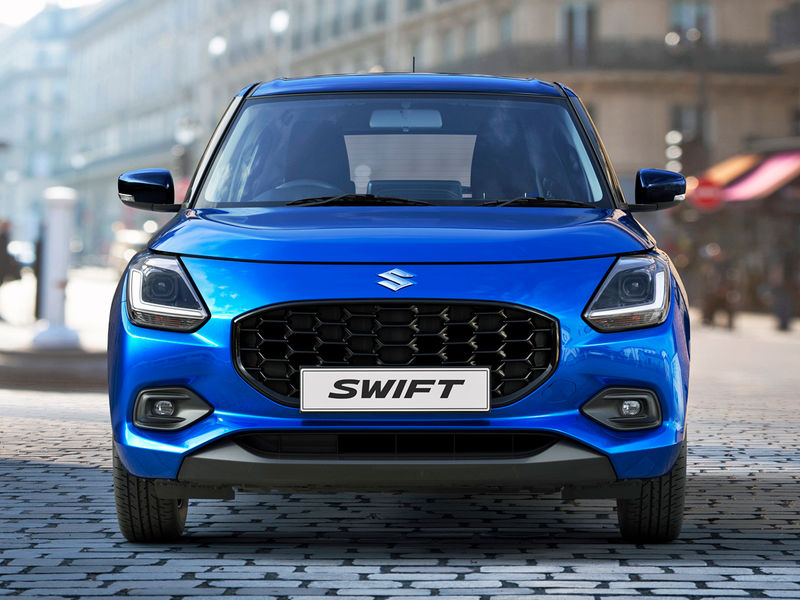
DrivePass gives you access to virtually new vehicles, from entry-level hatchbacks to larger family cars and SUVs. You can choose a vehicle that suits your needs and budget, subject to availability.
There are no traditional credit checks or requirements to submit bank statements and payslips. A poor credit score does not prevent you from using the offering.
How does it work?
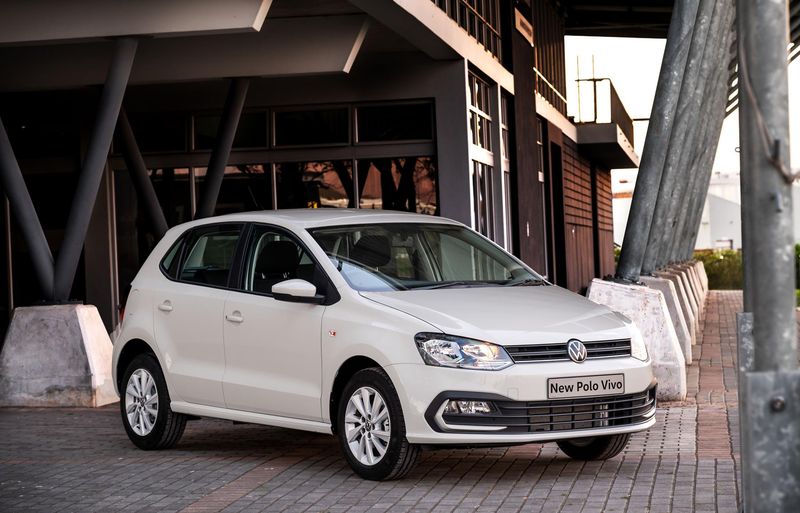
Choose your car, pay a refundable deposit and your first 30 days upfront, then top up your account for each additional 30-day period.
There is no long-term lock-in, and you can change or cancel your plan without cancellation penalties. To cancel, return the vehicle and end your subscription.
Your monthly payment includes insurance, servicing, maintenance, warranty and tracking. You don’t even need to worry about routine tyre replacement. Pretty much, add fuel and go.
There is a mileage allowance, with additional charges if you exceed it. Tolls and traffic fines are separate.
You need an eligible payment card and a valid driver’s licence first issued more than a year ago.
Card requirements vary by subscription price.
The subscription does not automatically transfer ownership to you. However, you can explore buying the car at any stage. If your credit profile improves and you qualify for finance, DrivePass can help facilitate the purchase.
Browse available DrivePass cars and monthly prices
What does rent-to-own actually mean?
Rent-to-own generally allows you to use a vehicle while making payments over an agreed term. Ownership depends on completing the requirements in the contract, which may include a final purchase payment.
Getting the keys does not mean the car is yours. You need to establish exactly when ownership transfers and what you must pay to get there.
Why you should approach rent-to-own cautiously
1. Ownership can be years away
Some agreements require payments for 4.5 to 5 years. That is a substantial commitment, particularly if you are already working to repair your finances.
Ask yourself whether the payment will remain affordable if your income falls or household expenses rise. A manageable payment today does not guarantee a manageable commitment for the full term.
You also need to consider the age and condition of the car you will eventually own after those years of payments.
2. The monthly payment can disguise the full cost
Rent-to-own can be an expensive route to ownership. The vehicle’s price may exceed its market value, and the total paid over the contract can be substantially higher than with traditional vehicle finance.
Calculate the upfront payment, every rental payment, fees and any final purchase amount. Then establish which running costs are additional. Insurance and maintenance are not included in every offering.
An accessible approval process does not necessarily mean good value.
3. You could pay for years and still leave without a car
If you cannot complete the ownership requirements, you may have paid substantial amounts without acquiring the vehicle.
In that situation, the promise of ownership has effectively delivered paid use of a car – and potentially an expensive rental at that. Depending on the contract, ending early can also carry financial consequences.
Before signing, ask what happens to payments already made and whether you will owe anything after returning the vehicle. Do not assume those payments become savings you can recover or put towards another car.
4. The car itself may bring additional costs
Vehicle age, condition and maintenance cover varies between providers. Some rent-to-own offerings involve older, higher-mileage cars that may need frequent repairs.
Check the vehicle’s condition and establish who pays when something goes wrong. Paying towards eventual ownership is less appealing if you are also funding significant repairs along the way.
5. A final payment could stand between you and ownership
Completing the monthly payments may not be the last step. Some agreements require a final lump sum before ownership transfers.
Establish that amount upfront and include it in your calculations. If you cannot afford the final payment, you may reach the end of the rental term without being able to buy the car.
Compare the commitment – not just the promise
Rent-to-own may suit some buyers, but the ownership promise should earn its place in your budget.
Compare actual quotes: upfront costs, monthly payments, included services, vehicle condition, ownership requirements and exit terms.
If your immediate priority is reliable transport while you improve your financial position, DrivePass offers a practical alternative: access to a virtually new car, bundled running costs and the flexibility to continue 30 days at a time.
You can meet today’s transport needs and revisit purchasing when you are better placed to do so.
Keep working on your credit profile
Alongside meeting your transport needs, review your credit report, address incorrect information and work towards keeping payments up to date.
Treat improving your credit profile as a separate task. Using a car subscription should not be assumed to improve your credit score automatically.
If your credit profile improves and you qualify for vehicle finance, DrivePass can help you explore purchasing the car you are driving.
Cars.co.za
Providing you with the latest motoring news, new car releases and the simplest way to buy and sell cars.